Behind a credit score sits a chain of data decisions
Equifax’s proposed U.S. settlement brings credit records, calculated scores and the status of a legal remedy into separate focus.

3 min read
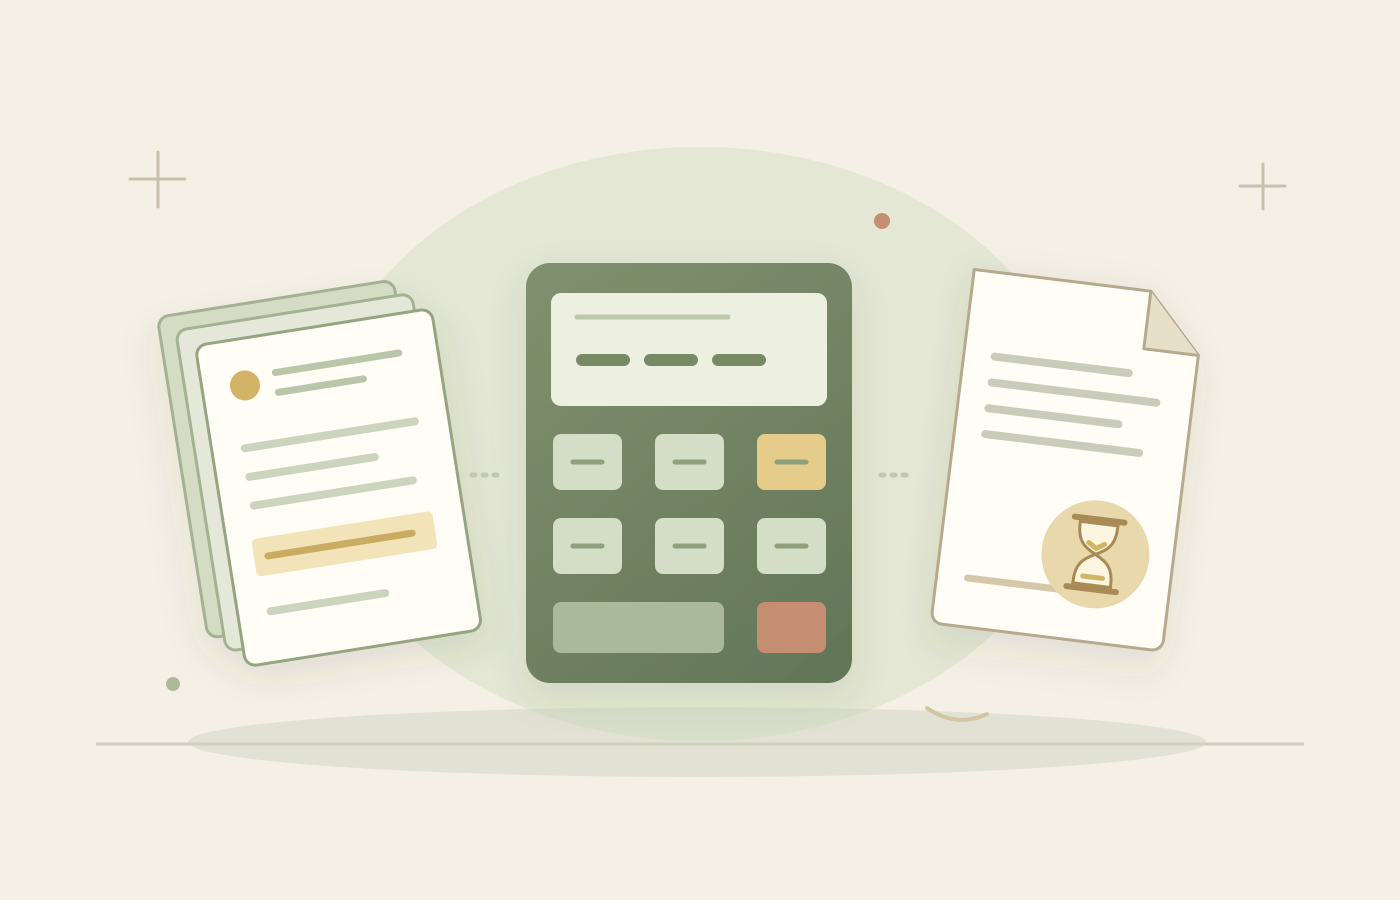
A credit score compresses information into a number that can influence an important decision. Understanding that number means looking at more than the display on a screen. There is a record behind it, a method used to calculate it and a context in which someone relies on it.
CNBC Select reported on the proposed Equifax credit-reporting settlement on October 23. The U.S. litigation concerns a coding issue in 2022 and information supplied to third parties. It offers a useful case for separating three questions: what a record contains, how a score is calculated and what a legal agreement resolves.
Equifax's own quarterly filing describes a previously disclosed coding issue that affected how some credit scores were calculated during a three-week period. It says the parties reached an agreement in principle in June 2026 and that the court later granted preliminary approval. Those are procedural developments, rather than a finding that the disputed claims have been proved.
A report and a score do different work
The Consumer Financial Protection Bureau describes a credit report as information about credit activity and current circumstances, including payment history and account status. A credit score is calculated from report information. The report is the underlying account of activity; the score is a calculation based on that account.
The CFPB also explains that a person can have many scores. Results can vary with the reporting agency, scoring model, type of credit product and calculation date. A difference between two numbers therefore needs context before it can be understood. The agency, model and date are part of that context.
Checking the information raises a different set of questions. In its guidance on common report errors, the CFPB lists mixed files involving another person, closed accounts shown as open, repeated debts and incorrect balances or credit limits. These concern identifiable entries in a record, rather than simply whether the overall score looks pleasing.
Keep the legal outcome separate
The settlement administrator's FAQ says the court has preliminarily approved the proposed agreement, while final approval remains pending. A final approval hearing is scheduled for January 22, 2027. Equifax denies wrongdoing, and the administrator says the court has not decided which side is right. A scheduled hearing is not final approval.
That distinction matters when reading the headline. A proposed agreement, an effective settlement and a demonstrated problem in an individual record are different propositions. The size or prominence of a case cannot, on its own, establish what a particular person's current report contains. Each question requires its own evidence.
Follow the information through the system
For readers assessing a data-driven service, the broader lesson is to identify the input, the transformation and the decision that follows. This is an editorial way to examine the system, rather than an independent test of Equifax's software. It keeps a concise output from standing in for the entire process.
The same care helps explain the news: describe the calculation issue at the scope the evidence supports, label disputed claims as disputed and preserve the difference between a proposed remedy and a completed outcome. A useful explanation makes those stages visible instead of compressing them into another single number.