A savings goal needs an amount and a date
A planned expense and an emergency serve different purposes. Comparing a target with available cash shows whether the schedule fits.

3 min read
A cost can be predictable without arriving every month. A future gift, an annual charge or a planned trip may stay outside the everyday bill-paying routine until its deadline approaches. The planning problem is to connect that future expense with the money available before it arrives.
CNBC Select’s October 29 feature describes a sinking fund as saving toward a large or irregular expense, using holiday purchases as its example. The useful idea is to give an anticipated cost a purpose and a time horizon within the household’s broader plan.
Name the kind of expense
The Consumer Financial Protection Bureau defines an emergency fund as money reserved for unplanned expenses or financial emergencies. Its examples include repairs, medical bills and lost income. The amount needed depends on the person’s circumstances; the guide does not prescribe one universal target.
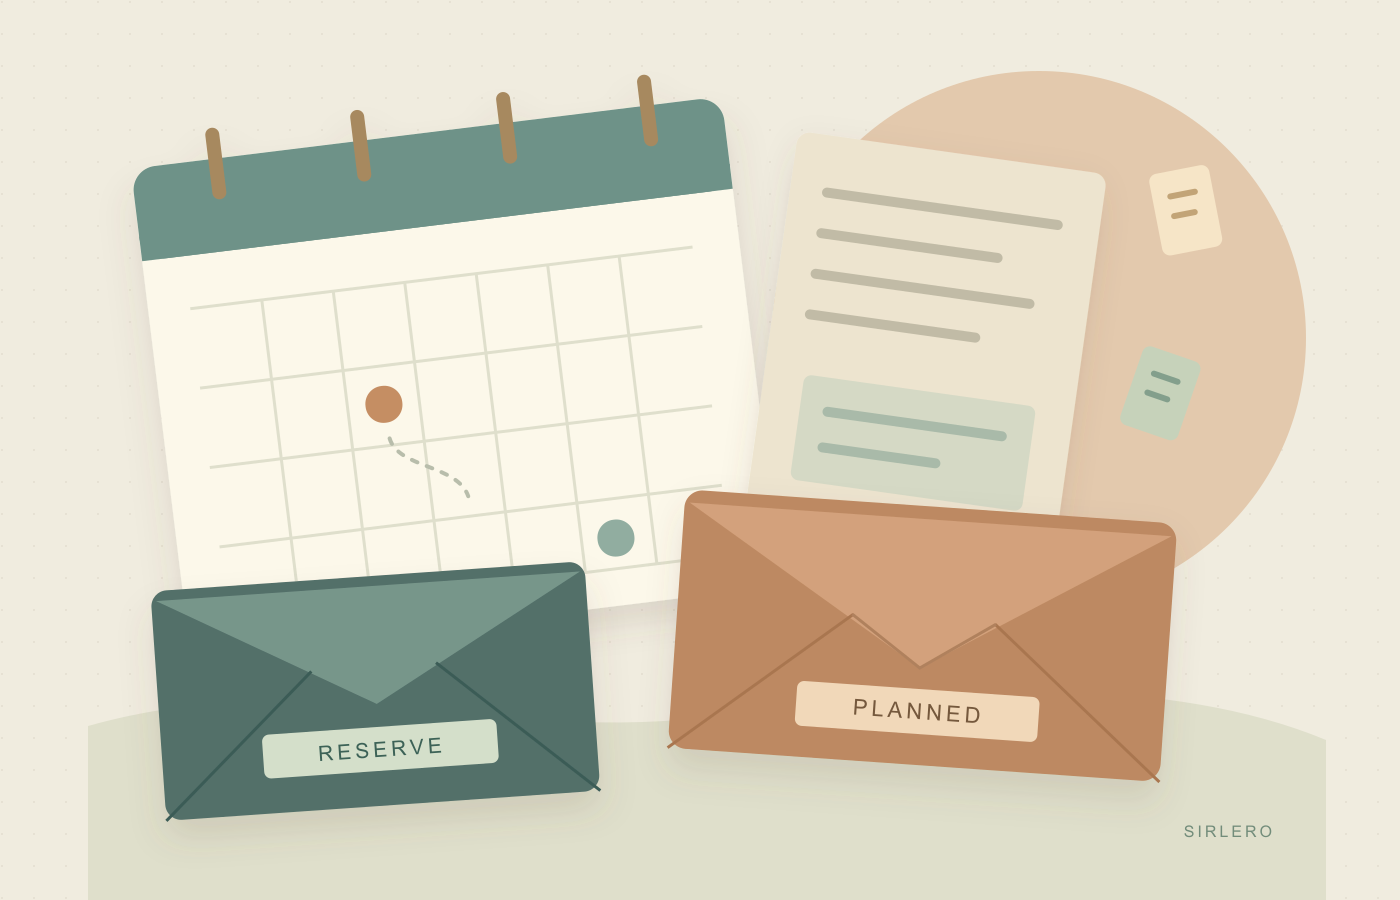
A planned annual charge and an unexpected repair can both require cash, but the planning questions differ. One has an anticipated deadline; the other involves uncertainty about what might happen. Giving these purposes different names makes it clearer what a saved amount is intended to do.
Separate the target from the capacity
The CFPB’s My new money goal worksheet starts with an amount and a deadline, then calculates a monthly saving requirement. It separately examines income, expenses and existing savings commitments to estimate what remains available. If that capacity falls short, the worksheet offers adjustments such as changing the goal amount or allowing more time.
Consider a hypothetical plan with a defined cost and a few income payments before the deadline. Dividing the target across those payments describes the proposed schedule. It does not establish that the household has that amount left after other commitments. The calculation and its feasibility answer different questions.
In its homebuying guide, the CFPB advises looking back over several months of spending to capture less frequent costs, including seasonal expenses and gifts. It also says a current budget should describe actual spending rather than an imagined version of what someone could or should spend.
That distinction has a broader planning use. A goal can look manageable when other expenses disappear from the page. Bringing them back may change the proposed timetable. The mismatch makes the assumptions visible and creates something concrete to reconsider: the goal, the deadline or the expected capacity.
Look at the intervals between payments
The CNBC feature connects its holiday target to successive paychecks. A hypothetical calendar can make that sequence visible: when money is expected, when the expense falls due and which other commitments occupy the intervals. Each proposed contribution then has an identifiable place in the schedule, along with its assumptions about available income.
For Sirlero, the value of this approach is the question it makes explicit. What is the money for, when will it be needed and what capacity exists along the way? A dated savings goal becomes easier to assess when those answers remain connected. The resulting plan can then be understood in the circumstances it actually has to fit.